
CEO of our portfolio software company, said that over the long term, stock returns will be determined largely by the CEO’s capital allocation decisions. Two companies with identical operating results and different approaches to allocating capital will derive two very different long-term outcomes for shareholders.
One of our main criteria in selecting our investment is how efficiently the company is allocating capital and creating value for shareholders over the long run.
We ask is the business highly profitable and investing enough capital to grow and protect itself from the competition?
However, it’s not just allocating capital that matters but you need to generate a higher return on capital.
You also need plenty of opportunities for reinvestment at a higher rate to repeat the process continuously and play a critical role in lasting value for shareholders.
Consider this: If you were to buy a business that earns a 5% return on capital over the next 20 years your investment will not be much even if you buy it at a significant discount.
However, a quality business that generates a 20% return on capital a year over the next 20 years even if you pay a premium will end up with great results.
We believe the best businesses do the latter, for extended periods and investors are successfully rewarded.
It’s for this reason we believe this metric is one of the most important parts of our investment strategy.
Companies with durable competitive advantage generate a high return on capital with minimal capital expenditure.
For instance, a business with 20% capital expenditure enjoys a substantial reinvestment advantage over one burdened with 80% capital expenditure.
If you have high capital expenditure in this example we will use 80% you need more money to invest in the future and your business becomes susceptible to competition.
Moreover, if it’s also low capital required for competitors or new entrants to compete that makes the company very fragile to disruption.
For example, Taiwan Semiconductor is one of the best classes in manufacturing the latest chips for artificial intelligence. Its significant capital requirement and specialised expertise create a formidable barrier to entry, securing its competitive advantage.
It will require more than hundreds of billions of capital to compete at their level. There is also not enough expertise in the field even if you manage to raise the money which provides a greater edge for the firm to shield itself from competition.
Capitalism is harsh if you are successful it will attract new competition and if you are not successful competition will disrupt your business.
According to McKinsey, on average the best and worst businesses across industries in allocating capital excluding goodwill:
| Best Capital Allocator Industry | Worst Capital Allocator Industry |
| Pharmaceuticals & biotechnology | Utilities |
| Household personal products | Telecommunication services |
| Software services | Transportation |
| Media | Energy |
| Commercial services & supplies | Materials |
| Semiconductors & equipment | Retailing |
| Healthcare | Food staples retailing |
| Food, beverage, tobacco | Consumer durable, apparel |
| Consumer Services | Capital goods |
| Technology hardware, equipment | Automobile components |
Source: Mckinsey
Historically the best industries created significant wealth for shareholders while the worst industries came out as bad in allocating capital and wealth creation for shareholders.
Our investment philosophy is straightforward: focus on industries with minimal competition and exceptional leaders skilled in capital allocation. Following Charlie Munger’s wisdom, we aim to “fish where the fish are” — seeking out fertile grounds for long-term wealth creation for our shareholders. This approach not only aligns with our commitment to prudent investment but also encapsulates our vision for sustainable long term success.
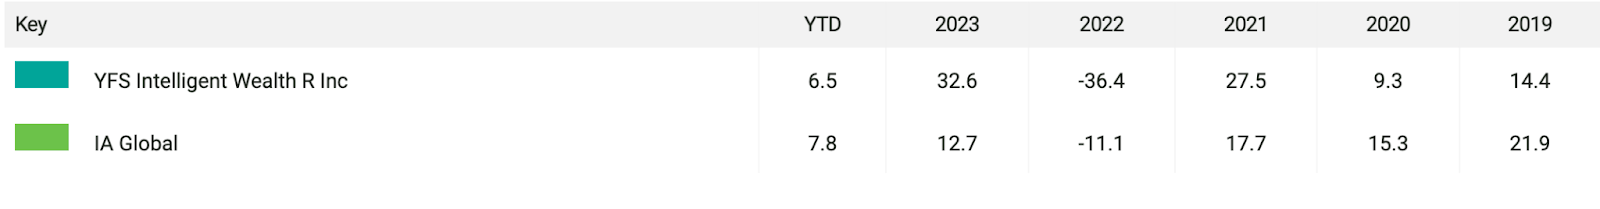
YFS Intelligent Wealth Fund Performance vs. IA Global
Awet Ghirmay, Head of Investment Research
If you want to learn more about this topic, please find the link here.
More information about our fund can be found here: Hargreaves Lansdown or AJ Bell
Risk warnings
The value of investments and the income derived from them may fall as well as rise. You may not get back what you invest. This communication is for general information only and is not intended to be individual advice. You are recommended to seek competent professional advice before taking any action. All statements concerning the tax treatment of products and their benefits are based on our understanding of current tax law and HM Revenue and Customs practice. Levels and bases of tax relief are subject to change. This blog is based on my own observations and opinions.


