
The UK’s State Pension system is facing a funding crisis.
With an aging population and increasing life expectancy, the pressure on taxpayers to fund pensions is intensifying.
Radical solutions are needed to ensure long-term sustainability.
One intriguing idea that could be used is a proposal from the US.
Billionaire investor Bill Ackman, suggests giving every child $7,000 (approximately £5,700) at birth, invested in a low-cost equity fund.
Over time, compounding could turn this sum into a significant retirement pot, reducing reliance on a State Pension.
Could this idea address the UK’s pension woes?
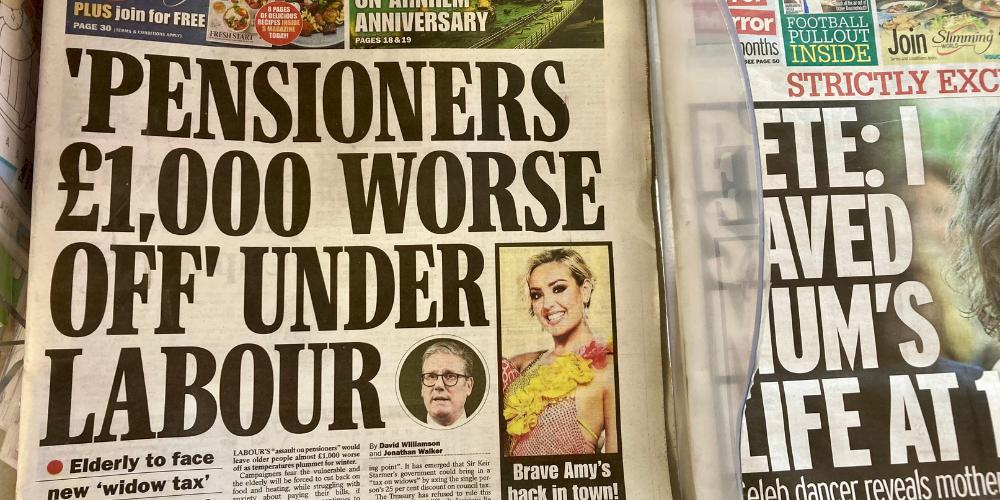
The UK State Pension Crisis
The UK’s State Pension system is funded on a pay-as-you-go basis, meaning today’s taxpayers fund the pensions of current retirees. However, demographic trends are creating a perfect storm:
- Aging Population: By 2050, nearly one in four people in the UK will be over 65, significantly increasing the number of pensioners.
- Rising Costs: The full new State Pension is currently £221.20 per week (£11,502 annually). With more people living longer, the cost to taxpayers is ballooning.
- Shrinking Workforce: Fewer workers are available to support each retiree. In 1950, there were about five workers per pensioner; by 2050, this ratio could drop to just two workers per pensioner.
- Political Resistance: Raising taxes or the retirement age, two obvious solutions, are deeply unpopular and politically challenging.
These factors make the current system increasingly unsustainable, prompting calls for innovative approaches.
Bill Ackman’s $7,000 Solution
Ackman’s proposal is simple yet radical: at birth, each child receives $7,000, invested in a diversified equity fund. The investment would grow tax-free and be locked until retirement age.
Here’s why this idea holds promise:
- Power of Compounding: Assuming an average annual return of 8% (historical returns for equities), $7,000 could grow to over $1 million by age 65. This provides a substantial nest egg for retirement.
- Reduced Reliance on the State: If individuals have their own retirement pot, the burden on the State Pension system decreases.
- Equity Ownership for All: This democratises wealth creation, giving every citizen a stake in the global economy.
For the UK, adopting a similar scheme could transform retirement planning. However, challenges remain.
Funding the Proposal
The most obvious hurdle is funding. Providing £5,700 to every child born in the UK would cost around £4 billion annually, based on approximately 700,000 births per year. This upfront cost could be funded through:
- Reallocating Resources: Redirecting funds from less effective programs.
- Corporate Contributions: Encouraging businesses to contribute as part of corporate social responsibility.
- Government Debt: Borrowing to invest in future generations, justified by the long-term savings from reduced pension obligations.
While expensive, this investment could pay off by alleviating future taxpayer burdens and fostering a more sustainable pension system.
The Case for Long-Term Investing in Stocks
Ackman’s proposal hinges on the superior returns of equities over the long term. Historically, stocks have outperformed other asset classes, making them the ideal choice for long-term investors.
Over the past century, global equities have delivered average annualised returns of around 8-10%, far surpassing bonds and cash.
Reinvested dividends and capital gains create exponential growth over time, a phenomenon magnified by starting early.
Stocks tend to outpace inflation, preserving purchasing power, whereas cash and bonds often lose value in real terms.
Investing in stocks means owning a share of the global economy, which tends to grow over time.
For those with decades until retirement, like newborns under Ackman’s plan, equities are unmatched in their ability to build wealth.
Critics might argue that equities are too volatile. While short-term fluctuations are inevitable, long-term investors benefit from market recoveries. Historical data shows that the longer the investment horizon, the lower the risk of loss. Diversification across global markets further mitigates risk.
Ackman’s idea also highlights the importance of starting early and embracing equity investments in personal retirement planning. For those already saving for retirement, key takeaways include:
- Start Early: The sooner you invest, the more time compounding can work its magic.
- Focus on Equities: For long-term goals, stocks provide the best growth potential.
- Diversify: Spread investments across geographies and sectors to reduce risk.
- Stay the Course: Avoid panic selling during market downturns; time in the market beats timing the market.
While Ackman’s $7,000 proposal is ambitious, it’s a thought-provoking solution to the UK’s pension crisis.
By leveraging the power of long-term equity investing, this idea could empower individuals, reduce reliance on the State Pension, and foster a culture of financial independence.
Adopting such a scheme in the UK would require political will, public support, and a willingness to embrace bold, long-term thinking. But as the pension crisis deepens, innovative ideas like Ackman’s may hold the key to ensuring retirement security for future generations while easing the burden on taxpayers.
Ultimately, the success of any retirement plan, whether personal or systemic, lies in harnessing the unparalleled wealth-building potential of equities.
Whether you’re a policymaker or an individual saver, the lesson is clear: invest early, invest wisely, and let compounding do the rest.
Carl Roberts, Director
If you want to learn more about this topic, please find the link
More information about our fund the YFS Intelligent Wealth Fund can be found here: Hargreaves Lansdown or AJ Bell
Risk warnings
The value of investments and the income derived from them may fall as well as rise. You may not get back what you invest. This communication is for general information only and is not intended to be individual advice. You are recommended to seek competent professional advice before taking any action. All statements concerning the tax treatment of products and their benefits are based on our understanding of current tax law and HM Revenue and Customs practice. Levels and bases of tax relief are subject to change. This blog is based on my own observations and opinions.


